Why Depreciation Accuracy Starts Before the Asset Reaches Finance
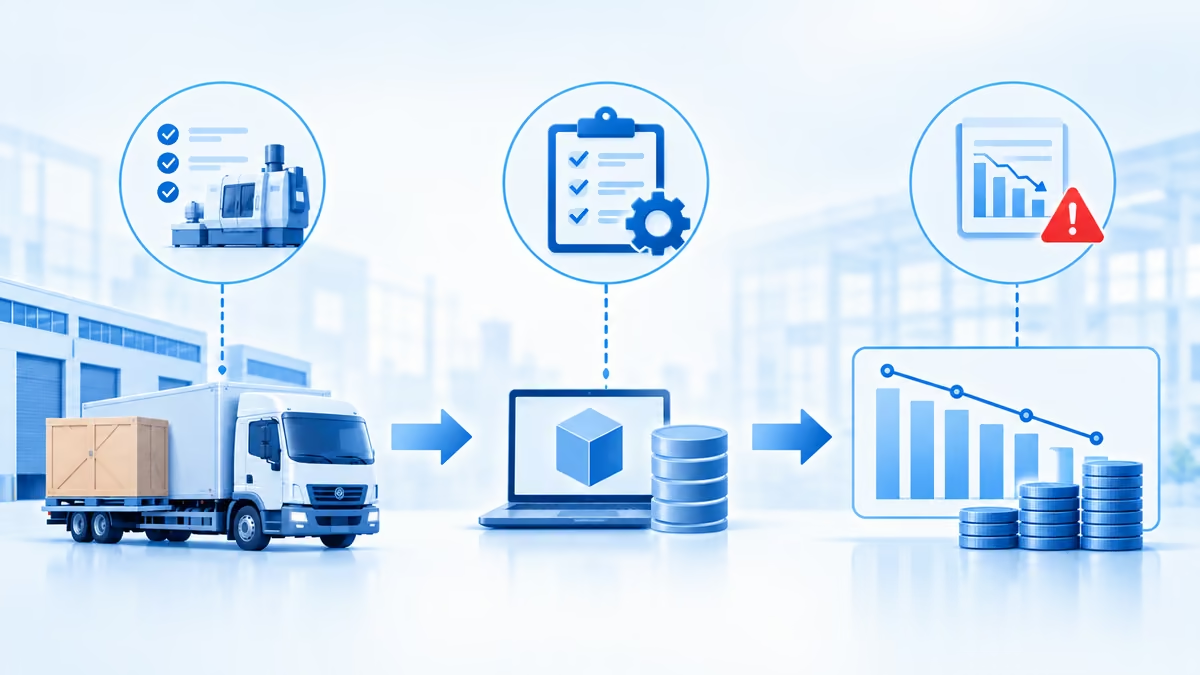
When a company buys machinery, computers, vehicles or specialised equipment, the finance team has to work out how much value those assets lose over their useful lives. That process is called depreciation. The arithmetic looks simple. But the accuracy of the result depends almost entirely on the information captured when the asset first enters the business: its cost, its category, its dates and its documents.
A small mistake at the purchase or registration stage can distort depreciation for years. A wrong acquisition date, a misclassified asset or a missing installation cost quietly affects every financial statement that follows. This is why depreciation is not only a finance task. It needs procurement, operations and accounting to work from the same, verified information.
It is also why finance teams evaluating fixed asset depreciation software should look beyond the calculation engine. This article explains what must be right at registration, and how depreciation software for Indian companies can help keep it right.
Quick answer: Depreciation accuracy starts before an asset reaches finance because depreciation is calculated from details recorded at purchase and installation: cost, acquisition and ready-for-use dates, asset category, useful life and residual value. If any of these are wrong when the asset is registered, every later depreciation entry carries the error forward. Verifying asset details before they are recorded, and automating depreciation from a central register, prevents most of these problems.
What is fixed asset depreciation?
Fixed asset depreciation is the systematic allocation of a tangible asset's cost over the period the business expects to use it. Suppose a company buys machinery for ₹10 lakh and expects to use it for ten years. Using the straight-line method with no residual value, it records ₹1 lakh of depreciation every year.
That does not mean the company pays ₹1 lakh every year. The purchase was paid for in full. Depreciation is an accounting mechanism that spreads the cost across the years in which the asset helps earn revenue.
To calculate it, the finance team needs four things: the asset's cost, its useful life, its expected residual value and the depreciation method. In India, companies commonly choose between the straight-line and written down value methods under their accounting policy. Schedule II to the Companies Act, 2013 gives indicative useful lives, and income-tax depreciation follows a separate block-of-assets approach, so the same asset can carry different figures for accounting and for tax. Our guide to how depreciation works for fixed assets explains each method with formulas and examples.
What asset information is needed to calculate depreciation accurately?
Finance teams cannot calculate depreciation accurately when the data they receive is incomplete or wrong. Before an asset moves into the accounting system, these details need to be confirmed:
- Purchase cost and supporting documents: the invoice value, with the purchase order, delivery challan and invoice to back it up.
- Directly attributable costs: eligible freight, installation, commissioning and similar costs needed to bring the asset to working condition.
- Acquisition date and ready-for-use date: the date the asset was acquired and the date it became available for its intended use.
- Asset classification: whether the purchase is a fixed asset at all or should be expensed, and which category it belongs to: plant and machinery, furniture, vehicles or IT equipment.
- Useful life and residual value: the expected period of use and the estimated value at the end of it, as set by the company's accounting policy.
- Location and ownership: the plant, department or business unit that holds the asset, and who is responsible for it.
When these details are recorded accurately, the finance team starts from a much firmer foundation.
How do early errors flow into depreciation?
Take the ₹10 lakh machine again, with a ten-year life and no residual value. Its invoice value is ₹10 lakh, but ₹2 lakh was also spent on freight, installation and commissioning. The correct capitalised cost is ₹12 lakh, so annual depreciation should be ₹1.2 lakh. The table shows how three ordinary entry mistakes change the result.
| Entry mistake | What goes wrong | Illustrative effect |
|---|---|---|
| Freight and installation left out of cost | Asset is capitalised at ₹10 lakh instead of ₹12 lakh | Depreciation of ₹1 lakh a year instead of ₹1.2 lakh: understated by ₹20,000 every year, ₹2 lakh over ten years |
| Wrong asset category | Machine is booked as office equipment with a five-year life instead of ten years | Depreciation of ₹2.4 lakh a year instead of ₹1.2 lakh: overstated by ₹1.2 lakh every year |
| Invoice date used instead of ready-for-use date | Depreciation starts about 74 days early, from 28 March instead of 10 June | About ₹24,000 charged for a period when the machine was not yet ready for use, and part of it in the wrong financial year |
None of these errors involves a wrong formula. The formula did exactly what it was told. The inputs were wrong, and the mistake repeats until someone finds it.
The same logic applies to the date. Under Ind AS 16, depreciation begins when the asset is available for use, not when the purchase order is raised or the invoice is received. If installation takes weeks, the ready-for-use date has to come from the people who installed and commissioned it, not from the purchase documents alone.
What is the asset capitalisation process?
Asset capitalisation is the step where a qualifying expenditure is recorded as a fixed asset on the balance sheet instead of being expensed immediately. Not every purchase qualifies. Most companies follow a capitalisation policy based on value thresholds, expected useful life and applicable accounting standards.
A typical process runs in six steps:
- Purchase and documentation: procurement raises the purchase order and collects the invoice, delivery documents and approvals.
- Asset identification: the company checks whether the purchase meets its capitalisation criteria.
- Cost assessment: eligible costs of bringing the asset to its location and working condition are identified and added.
- Asset classification: the asset is placed in the right category, such as machinery, furniture, vehicles or IT equipment.
- Capitalisation and registration: the asset is entered in the fixed asset register with its cost, acquisition details, location and custodian.
- Depreciation set-up: finance sets the useful life, residual value, method and start date under the applicable policy.
Every step feeds the next. A gap in step 1 or 3 cannot be fixed by careful work in step 6.
Why must procurement and finance coordinate on asset records?
Procurement usually records the cost, finance owns the accounting treatment, and operations or IT know when the asset was actually installed and put to use. If these three groups work from separate records, information is lost between them.
- Procurement should pass on complete purchase documents, asset specifications, serial numbers and delivery details.
- Stores or receiving should confirm what was received, in what condition and when.
- Operations, IT or administration should confirm installation, commissioning and the ready-for-use date.
- Finance should decide capitalisation, category, useful life and residual value under company policy.
Good coordination ensures that purchases, installations, transfers and disposals are all properly documented. It also means finance finds out about a missing installation bill when the asset is registered, not at year-end.
How do asset location and ownership affect depreciation records?
Location and ownership details do not change the depreciation formula, but they decide whether the figures can be trusted and used. They help finance teams to:
- Assign the depreciation charge to the right department, cost centre or business unit.
- Verify that each asset in the register physically exists, which is the basis of fixed asset verification.
- Carry an asset's cost and accumulated depreciation correctly when it is transferred between units.
- Stop depreciation at the right time when an asset is sold, scrapped or written off.
If an asset is recorded in the wrong place, or under an employee who has left, finance cannot easily tell whether it still exists, which makes verification and reconciliation slower. The link between asset location and reliable records is discussed in the difference between knowing where an asset was and where it is.
What are the audit and financial reporting implications?
Wrong depreciation inputs affect financial statements, asset valuations, budgets and audit results. Because depreciation recurs, the error is not a one-off. It repeats every period until it is found and corrected.
Ind AS 16 expects companies to review an asset's useful life and residual value at least at the end of each financial year, which only works if the starting data is traceable. Auditors will ask for the purchase documents, the capitalisation basis and evidence that the asset exists. When depreciation figures cannot be tied back to documents, the finance team spends audit time reconstructing history instead of answering questions.
How does fixed asset depreciation software improve accuracy?
Fixed asset depreciation software, or automated depreciation, calculates schedules from rules configured once, such as the method, useful life and residual value for each asset category. That removes manual formula errors and saves the monthly effort of rebuilding schedules in spreadsheets.
Automation does not fix wrong inputs, though. It applies the wrong cost or the wrong date just as faithfully as the right one. This is why fixed asset management software is most useful when it also improves what goes in: a central register that brings procurement details, invoices, asset categories, locations, useful lives and depreciation schedules together, and flags missing information before capitalisation. Bigsun's Financial Accounting Software (FAS) and ERP software are built to keep accounting and operational records connected, and our complete guide to fixed asset management software covers what to look for.
For businesses with assets spread across several sites, standardised registration and automated schedules also reduce the manual work needed to keep every location consistent. Companies that use Ind AS should also confirm how any software handles component accounting and the difference between book and tax depreciation, and ask the vendor to show it with their own asset classes.
How can businesses prevent depreciation errors from the beginning?
- Write down a registration procedure. Define who records what, and by when, from purchase to installation.
- Use a mandatory checklist. Cost, additional costs, acquisition date, ready-for-use date, category, useful life, residual value, location and custodian should all be confirmed before an asset is recorded.
- Verify before recording. Compare the invoice, purchase order and delivery documents with what was actually received and installed.
- Keep a clear capitalisation policy. Set thresholds, categories and useful lives so that everyone classifies assets the same way.
- Review periodically. Compare the register with physical verification and fix differences promptly.
The related problem of poor records in general is covered in Your Company Doesn't Have an Asset Problem. It Has an Asset Data Problem.
Final thoughts
Accurate depreciation does not begin when a number is typed into a spreadsheet. It begins the moment a business acquires an asset, secures its documents, establishes its value and records the right details for accounting.
Depreciation is central to financial accounting, but its precision depends on everyone involved in buying and bringing assets into the organisation. By strengthening the capitalisation workflow and keeping an accurate fixed asset register from day one, companies can make depreciation more consistent, improve the reliability of financial reporting and prevent problems that might otherwise persist for years.
If you are comparing fixed asset depreciation software, ask to see how it captures cost, dates and categories before it calculates anything. You can talk to the Bigsun team about how FAS and ERP would fit your finance and procurement process.
Get depreciation right from the first entry
See how connected accounting and operational records can help your finance, procurement and operations teams register assets correctly. Book a demo with the Bigsun team.